

In the first half of 2026, Italian commercial real estate attracted €7.034 billion of investment, 2% more than in the same period of the previous year. In the second quarter alone, volume stood at 4.4 billion, up 11% year on year.
The figure seems to describe a market back at full speed. The more interesting picture is more selective: capital has returned and is rewarding very different economic functions.
Retail and hotels lead on volume. Logistics, data centres, living and regeneration are attracting attention for different structural reasons. On residential, by contrast, Banca d’Italia reports demand that remains subdued, shrinking supply, slowing prices and rents accelerating compared with the previous quarter.
For a CEO or CFO, the issue is above all one of capital allocation: a property can absorb resources, release them, support operations or become a constraint that is hard to reverse. The useful question is which economic function the capital is buying, and how consistent that function is with the direction of the business.
It is the same kind of reading that informs Executive Advisory: investments, scenarios and hard-to-reverse decisions are assessed before their structure becomes a fait accompli.
The Italian property market is not rising in unison
CBRE records €7.034 billion of commercial real estate investment in the first half of 2026. The last twelve months exceed €13.9 billion. Overall growth coexists with very wide differences between asset classes.
Where capital went in the first half of 2026
Investment volumes by asset class, in descending order
leading asset class by volume in the half-year
pipeline of around €1bn between late 2026 and early 2027
+43% year on year
interest in quality assets and deals above €100m
growth in digital infrastructure investment
volumes −42%, but first preference in the investor survey
Living is the anomaly: last by volume invested, down 42%, and at the same time investors' top stated preference. A gap between what capital says it wants and what it is actually buying.
Source to be specified. Order rearranged by descending volume compared with the original list.
The most useful contrast is precisely the one between actual flows and intentions. Retail is the leading asset class by capital invested in the half-year, with around €2.2 billion. In the CBRE Italian Investor Intentions Survey 2026, however, Living is the top stated preference, cited by 30% of the more than 200 investors surveyed, ahead of Industrial & Logistics and Hotels.
The survey also shows that around 70% of investors expect to maintain or increase their activity in Italy. The figure says something about interest in the market; volumes show where that capital has already arrived.
Properties that do something are gaining ground
This is where asset classes long considered “alternative” start to look far less alternative. Value is increasingly read through function: housing people, moving goods, processing data, organising services, sustaining a changing city.
Living is a good example. Student housing, build-to-rent and senior living build value around structural demand and a service, as well as ownership of the space. In the half, however, actual investment amounted to €264 million, down 42% year on year: strategic interest and capital already invested are not the same thing.
Logistics tells a different story. Industrial & Logistics attracted around 1.1 billion, up 43% year on year. CBRE also records take-up of around 1.6 million square metres in the half, up 72%, driven by manufacturing and industrial occupiers and by limited availability of quality properties.
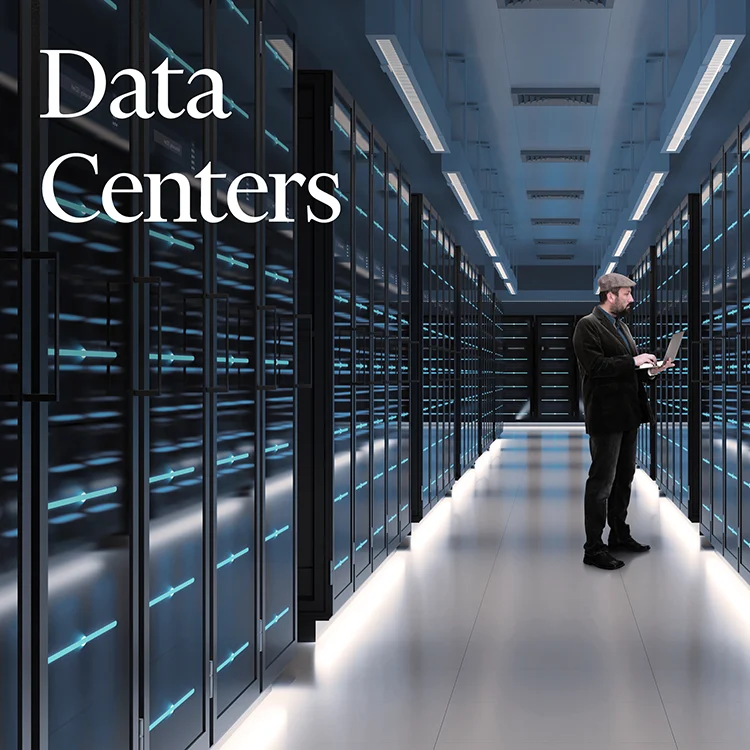
Data centres take this logic even further. Almost €600 million was invested during the half-year in land earmarked for their development. Here, property value is inseparable from energy, connectivity, permits and grid availability. The growth of artificial intelligence is creating demand for infrastructure that end consumers may never see and that requires growing amounts of physical capital.
Retail and hotels are a reminder that capital does not look only at the new
In the first half, Retail was the largest sector by volume, at around €2.2 billion, in line with 2025. The second quarter alone accounted for around 1.5 billion, driven by high streets, shopping centres, retail parks and outlets.
This dynamic matters because it corrects an overly simple reading of the market: growth does not belong solely to asset classes linked to technology or new housing models. Traditional properties can also become central again when location, quality, scarcity and income-generating capacity make them competitive.
Hotels attracted around 1.4 billion in the half. CBRE reports a pipeline of around one billion euros of deals expected between the end of 2026 and the first months of 2027, and growing scouting activity by Middle Eastern capital.
In hospitality, real estate and operating business tend to overlap: brand, operator, positioning, destination and tourist flows all feed into the investment thesis together.
Regional cities now account for half of H1 investment
Another signal comes from geography. CBRE records around €3.5 billion invested in regional cities in the first half, mainly in Industrial & Logistics, Hotels and Retail.
Milan and Rome remain central, but a growing share of capital is also looking at regional markets with solid fundamentals, competitive yields and repositioning potential. Value can stem from a change of use, the quality of the project or new infrastructure, even before any change in the city’s average price.
Residential reflects a different market
In the second quarter of 2026, Banca d’Italia recorded a slowdown in sale prices, a slight year-on-year decline in agency-brokered transactions and still subdued demand. Supply continues to shrink and selling times remain at their lowest levels since the survey began.
Rents accelerated compared with the previous quarter across most of the country, while decelerating compared with the same quarter of 2025. The outlook reported by market operators points to a cautious improvement, especially over a two-year horizon.
For investors, then, scarcity is not enough. They need to distinguish where it stems from structural demand and where prices factor in expectations that have yet to be proven. Property quality, micro-location and intended use matter far more than the national average.
The theme of 2027 will be selection
2026 does not tell the story of an indiscriminate return to bricks and mortar. It tells the story of a new selectivity of capital.
Retail, Hotels and Industrial & Logistics currently lead volumes. Living and data centres, by contrast, show where a significant share of strategic attention is turning. The two can diverge for months or years, and it is precisely that gap that makes deeper analysis worthwhile.
For an investor, the question ‘where do I buy?’ is less useful than ‘what change am I buying?’. For a CEO or CFO the principle is similar: what function must that asset perform, how much capital does it tie up, and which alternatives is it making harder in future?
In the most significant transactions, a Due Intelligence can help to read scenario, demand, risk, dependencies and the consequences of the decision together, before capital is committed.
Where capital is really going
The picture of the Italian property market in 2026 is therefore less linear than the headline figure suggests. Capital has returned and is asking more of properties at once: income, scarcity, function, infrastructure, capacity for transformation and genuine demand.
This is why a data centre site, a student residence, a well-connected warehouse, a hotel in a strong destination and a quality retail property can compete for the same capital despite belonging to different worlds.
To understand where capital will go in 2027, we will need to look less at a property’s label and more at the economic function that asset will be able to sustain.
30-minute conversation
Are you buying a property or deciding what your capital will have to do?
A thirty-minute conversation with the Bliss team to define the role the next property investment should play in the company’s strategy. We start from the decision, the objectives and the alternatives to be assessed in practical terms.
Domande frequenti
Why is the Italian property market still of interest to investors in 2026?
Because Italian commercial real estate is sustaining high volumes, access to debt remains relatively favourable and several asset classes show solid fundamentals. Interest is, however, selective: quality, income, infrastructure and value-creation potential matter more than simply belonging to a category.
Which property asset classes are attracting the most attention?
By actual volumes in the first half of 2026, Retail, Hotels and Industrial & Logistics lead. In investor intentions, Living is the top preference, while Data Centres are emerging as an infrastructure asset linked to the growth of digital and AI.
Why are Living and Data Centres attracting so much attention?
Because they capture structural shifts. Living responds to housing demand, student housing and senior living; Data Centres depend on the growth of computing, cloud services and AI. In both cases, the value of the property is closely tied to the function it makes possible.
What could change in the Italian property market in 2027?
Selection may become even more important. Asset quality, availability of infrastructure, income-generating capacity and genuine demand will tend to carry more weight than simple average price growth.
How can Bliss help a CEO or a Board assess a property investment?
Bliss does not replace property advisers, technical consultants or lawyers. It can support senior leadership in the strategic reading of the decision: alignment with the company’s direction, capital tied up, scenarios, dependencies, alternatives and impact on the brand or the operating model. In Executive Advisory mandates, this type of investment is assessed before it becomes difficult to reverse.
Fonti e riferimenti
- CBRE Italy, Commercial Real Estate in Italia: 4,4 miliardi nel secondo trimestre 2026
- CBRE Italy, Il Commercial Real Estate italiano accelera verso una nuova fase di crescita e diversificazione
- Banca d’Italia, Sondaggio congiunturale sul mercato delle abitazioni in Italia - 2° trimestre 2026
- Bliss, Executive Advisory
- Bliss, Due Intelligence: cos’è, come funziona e perché riduce il rischio nelle decisioni aziendali
- Bliss, Intelligenza Artificiale: definizione, storia e prospettive