

The last few days have been demanding for the financial markets.
Between the labour market, the Fed and new scenarios for the US landscape, there is plenty to discuss ahead of Monday’s market open. Taking stock of the first ten days of July 2026, the summer is shaping up to be more eventful than it looked in June.
Let’s look at why.
The labour market
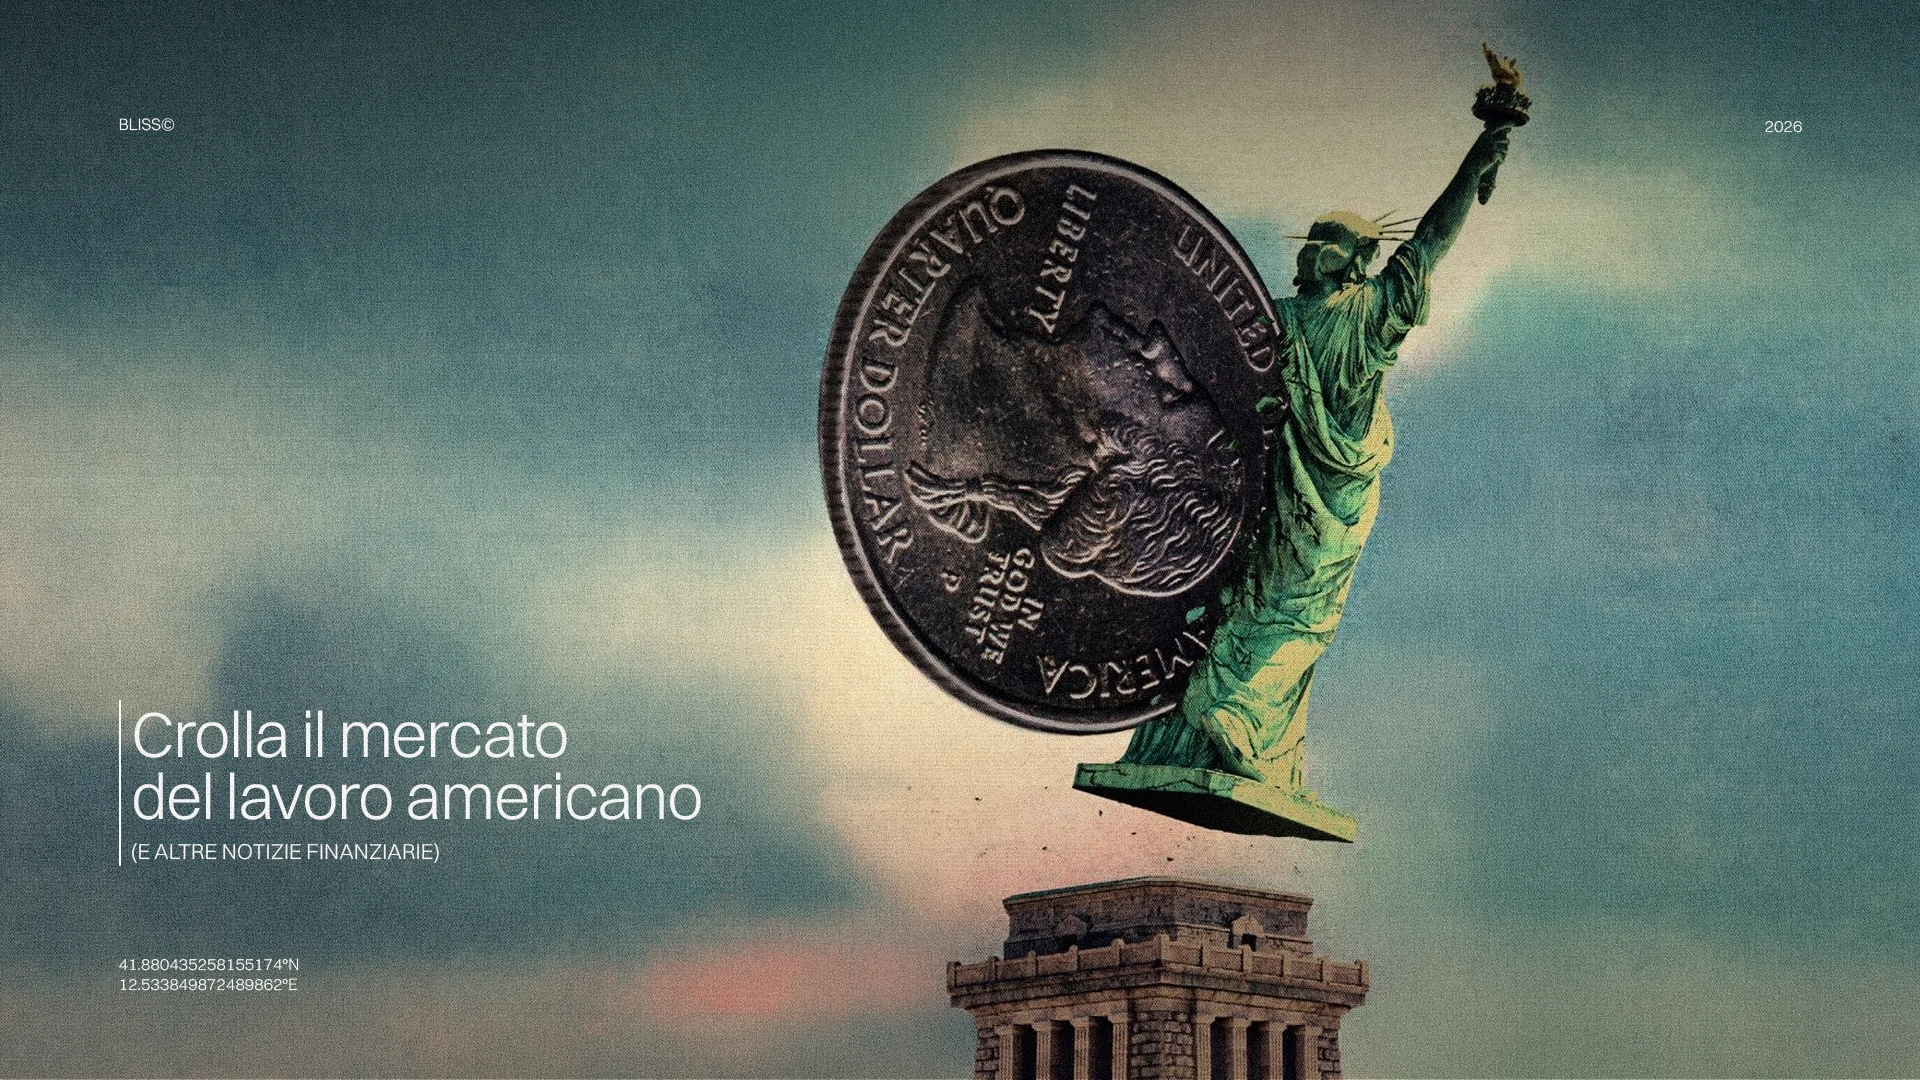
On 2 July, the Bureau of Labor Statistics published the US employment figure for June: +57,000 jobs. Expectations were 113,000.
Exactly half.
The number alone would make headlines. But the more significant figure comes straight after, in the revisions.
April falls from +179,000 to +148,000. May from +172,000 to +129,000. Seventy-four thousand jobs that existed last month are now gone. The US labour market is weaker than the narrative built over recent months has suggested.
The unemployment rate has fallen to 4.2%.
Sounds good? Not quite, because the reason is hardly reassuring: 0.3 percentage points fewer people are now looking for work. Since January the labour force has shrunk by 1.1 million people. When unemployment falls because people stop looking, the market is not improving.
Then there is the World Cup paradox.
The sector that should have benefited most from millions of fans arriving in American cities (food service and hospitality) lost 61,000 jobs in June. The World Cup, at least in the June survey, created no additional employment. The real impact will show up in the coming reports. Or it won’t.
One last figure to close this section: average hourly earnings are growing by 3.5% year on year. US inflation stands at 4.2%.
Every month, then, American workers are losing real purchasing power (0.7%).
The Fed on hold
Kevin Warsh, Chair of the Fed, held rates at 3.50%-3.75% for the fourth consecutive meeting.
So far, no surprise.
The surprise, instead, was his silence. In the post-meeting press conference he offered no forward-looking indication. No mention of July. No forward guidance. And a Fed Chair who says nothing concrete at a time when the labour market is slowing and inflation remains above target is not a good sign…
On 8 July, the minutes of the 16-17 June FOMC meeting were published. The message that emerges: inflation is still above the 2% target, and further hikes remain on the table. The Fed is watching and waiting.
The markets
The S&P 500 and Nasdaq closed a second consecutive week in the red: S&P -1.4%, Nasdaq -2.1%. Tech and AI under pressure, rotation into defensives. Bucking the trend, the Dow Jones reached a new all-time high. Morgan Stanley nonetheless maintains its S&P 500 target of 8,000 points, but the road looks bumpier than it did in the spring.
On 6 July, the ceasefire agreement between the United States and Iran gave Wall Street confidence, with the S&P 500 and the Nasdaq rallying by as much as 2%. The problem is that two days later the tensions returned, and with them the skirmishes, the closure of the Strait and, once again, the tension priced into US stocks.
Today more than ever, geopolitics remains the hardest variable to price.
Meanwhile, SpaceX has entered the Nasdaq 100, triggering forced buying by index funds estimated at $4.3 billion. Gold is close to its all-time highs. Private credit, a 2-3 trillion sector that has grown in the shadow of the banking system, is showing its first signs of fragility under the pressure of still-high interest rates.
From Italy
Here in Italy, meanwhile, Intesa Sanpaolo launched a €2.3 billion buyback on 6 July, and BPER one of up to €750 million. Italy’s major banks are returning capital to shareholders at a time when high rates are squeezing margins in the real economy and inflating them on bank balance sheets.
The dollar stands at 1.144 to the euro, down 0.85% over the past month: disappointment over the US labour market is reducing expectations of further Fed hikes and weakening the greenback.
New Connections (FAQ)
Is June’s collapse in employment a sign of imminent recession?
Analysts are split between two readings, both defensible. The first: 57,000 jobs, with 74,000 in downward revisions to previous months, describes a market that is clearly losing momentum. The second: the June figure includes seasonal distortions linked to the start of the World Cup, and healthcare continues to grow structurally. Unemployment at 4.2% does not yet signal a recession. What it signals is a faster-than-expected normalisation, at a time when the Fed still has no room to act because inflation remains above 4%.
Why isn’t the Fed cutting rates if the labour market is slowing?
Because the Fed’s dual mandate is full employment and price stability. With inflation at 4.2% and a 2% target, the Fed cannot cut without signalling that the fight against inflation is over before it has been won. Warsh chose silence precisely so as not to move in either direction: any explicit signal, whether a cut or a hike, would move markets at a time when the macro data are still deciding which way to go.
Does SpaceX joining the Nasdaq 100 change anything for those holding an index ETF?
Yes, mechanically. Funds tracking the Nasdaq 100 were obliged to buy SpaceX shares from 7 July to keep their composition aligned with the index. Analysts estimate $4.3 billion in forced buying. For anyone holding a Nasdaq 100 ETF, this now means having a share of exposure to SpaceX, a company that has never gone through the traditional listing process and does not publish financial statements with the same frequency and transparency as the index’s other constituents.